
After the Storm
Help With Your Storm Damage Claim
A hailstorm leaves you with a damaged house and an insurance process nobody ever taught you. Black Bison Roofing handles both with you, starting with a free look at the whole property.
Claim or Repair
Do You Even Have a Claim?
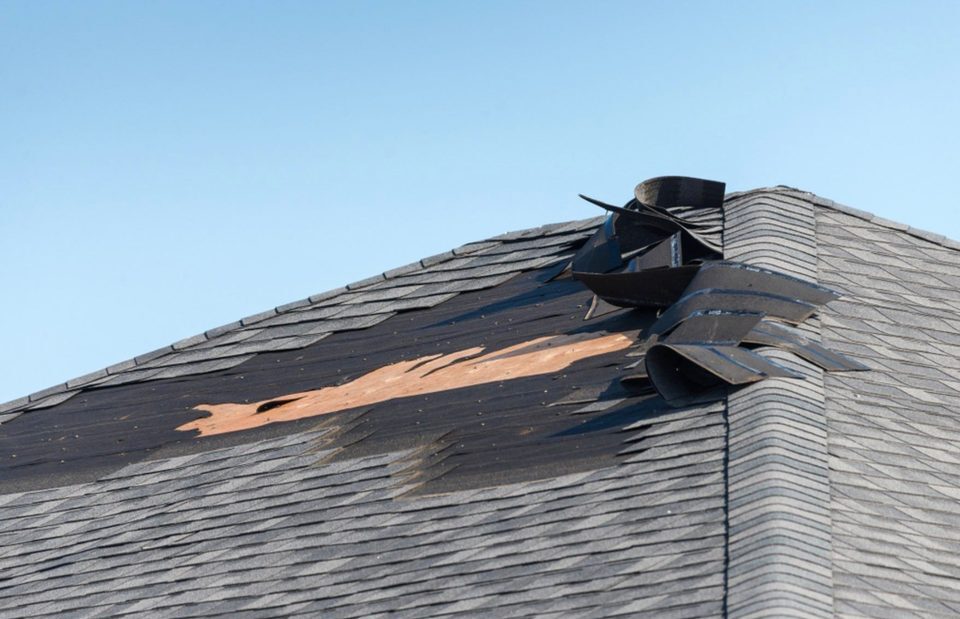
Not every hailstorm leaves a claim behind, and the only way to know is for somebody to get up on the roof and look. We inspect the whole property and walk you through the photos afterward, so you are looking at the same evidence we are.
Sometimes the answer is that the damage is small and a repair handles it. We would rather tell you it is a repair. You get that answer before anyone calls a carrier, not after.
The Claim, Step by Step
How Does a Roof Insurance Claim Work?
Your carrier makes the decision, so our job is to make sure it gets made on the full picture of the damage.
-
Step 1: We Look at the Whole Property.
Hail rarely stops at the roofline. The roof, the gutters, the siding, the fence, and the window screens all get photographed before anybody talks about filing. Anything left out of that record is hard to add back in later.
-
Step 2: We File It With You.
Carriers ask questions most homeowners have never heard before. We get on the call with you, so somebody on your side of it already knows what they are asking and why it matters.
-
Step 3: We Meet the Adjuster on the Roof.
The adjuster is the inspector your carrier sends out to put a number on the damage. We are there when they walk it, photos already in hand, so a fast pass does not become a short list.
-
Step 4: We Rebuild the Estimate.
Carrier estimates are written in Xactimate, the pricing software the insurance industry runs on. We work in that same software, put back the line items the first pass left off, and support each one with a photo. Approving them is still the carrier's call.
-
Step 5: The Money Comes in Stages.
Most claims pay twice: actual cash value first, which is the damage minus depreciation, then the depreciation itself once the work is finished. You hear that sequence, and your deductible, before the first check arrives.
Deductible Honesty
Your Deductible, Said Plainly
Your deductible is yours to pay, and you hear the number from us at the start rather than at the end. We will not waive it or fold it into the price. Texas made that a criminal offense in 2019, and it is not a line we go near.
Billing works the same way. You pay for the work we actually perform, so if part of an approved scope never gets built, it never lands on your invoice.

Inspection Scope
What a Whole-Property Inspection Covers
Storm damage spreads well past the shingles, so we look at everything the weather could have touched.
- The roof itself.Shingles, flashing, vents, and the ridge, photographed up close and from the ground.
- Gutters and downspouts.Dents, separations, and pulled fasteners documented alongside the roof damage.
- Siding, trim, and windows.Hail hits the walls of a house too, and that belongs in the same claim.
- Fencing and screens.Commonly damaged, commonly left off a claim, simple to capture while we are on site.
- Ceilings and interior walls.Where water has already made it inside, stains and soft sheetrock get recorded.
Homeowner Claim FAQ
Claim Questions Homeowners Ask
No. A good share of what we do is a straight repair with no carrier involved at all. The inspection tells us which situation you are in, and we tell you honestly.
That sits between you and your carrier, and we will not guess at it on their behalf. What we can do is make sure that if you file, you file on documented damage instead of a hunch.
It happens on a quick walk. The photo record and the rebuilt estimate exist for exactly that, and together they give your carrier a clear reason to look again.
That depends on your carrier and how many homes the storm hit. What we control is our end of it: the documentation, and the schedule once the work is funded.
Yes, with the same process at a larger scale. See commercial insurance claims.